
When Love Meets Money: The Psychology of Financial Compatibility
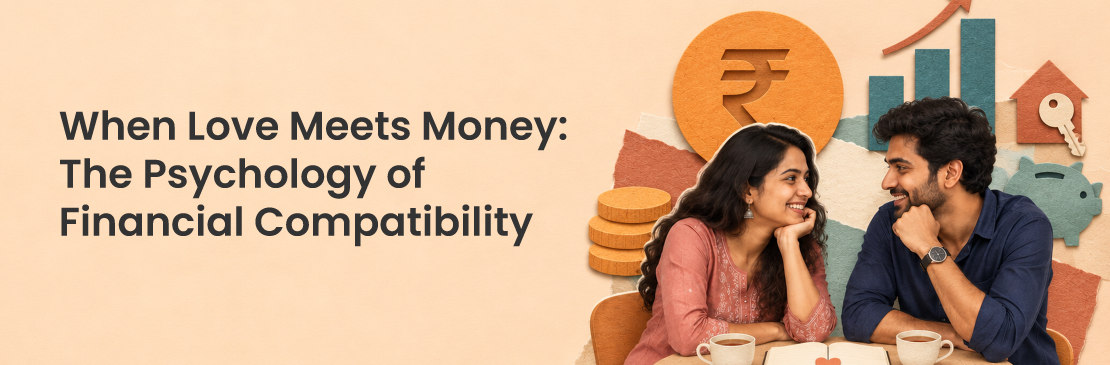
They say opposites attract. But what happens when one person loves spontaneous plans to travel, while the other would rather save every extra rupee towards their dream home?
Money has a way of causing tension in relationships, whether we talk about it or not. And financial compatibility isn’t simply about earning similar salaries, splitting bills equally or enjoying the same lifestyle. It’s understanding how two people think, feel and make decisions about money.
Your Money Personality Has a Backstory
Every relationship brings together two financial personalities. There’s the saver who finds comfort in a growing bank balance, the spender who believes money is meant to be enjoyed, the planner who has the next five years mapped out, and the risk-taker who’s comfortable with having just a thousand rupees in their account before the paycheque hits.
Most of us are a mix of these personalities, crafted by experiences that began long before our first paycheque.
Growing up inside a household where money was always tight might make someone cautious about spending. Someone raised in a financially comfortable environment may have a different relationship with risk and security.
Neither approach is automatically right or wrong. But understanding where your partner’s habits come from can replace judgement with understanding.
The Dialogues We Tend to Avoid
It’s easy to discuss holiday plans. Discussing outstanding loans, savings or financial responsibilities towards family? Not always.
Money conversations can feel uncomfortable because they touch on very personal things: independence, security, expectations and sometimes even shame.
But not talking about them can create bigger problems later.
Being open about earning, debt, loans and future goals isn’t about checking on each other. It’s about developing trust and making decisions with the full picture in mind.
Two People. One Shared Future
Being together doesn’t mean giving up your financial independence. Both partners have the freedom to make personal choices while also working towards common goals. That could look like having an individual savings account for themselves, and a joint account for a home, travel or long-term investments.
And when priorities differ? Talk about the why behind them. Maybe one partner likes to travel because experiences matter more to them. The other wants to own a home because they care about being stable. Understanding your partner better can lead to less friction.
Financial compatibility doesn’t require identical spending habits, matching investment portfolios or agreement on every purchase. All it needs is two partners who respect each other enough to have open and honest communication.

Do you have any questions? Write to us